How to Make a Budget That Actually Works: The Cash Flow Blueprint
Most budgets fail because they treat spending plans like rigid diets instead of timing tools. Learn how to map your cash flow to your paydays, protect your Four Walls, and build a system you will never abandon.
Educational Notice: This guide provides behavioral cash-flow planning principles. It does not provide individualized accounting, investment, or legal tax advice. Adapt every step to your specific payroll schedule and household bills.
The Reality Check (Read This First)
- Budgeting is timing, not restriction: Most people do not run out of money because they overspent on coffee. They run out because large bills are due on the 1st, while their paychecks arrive on the 15th and 30th. Timing beats willpower every time.
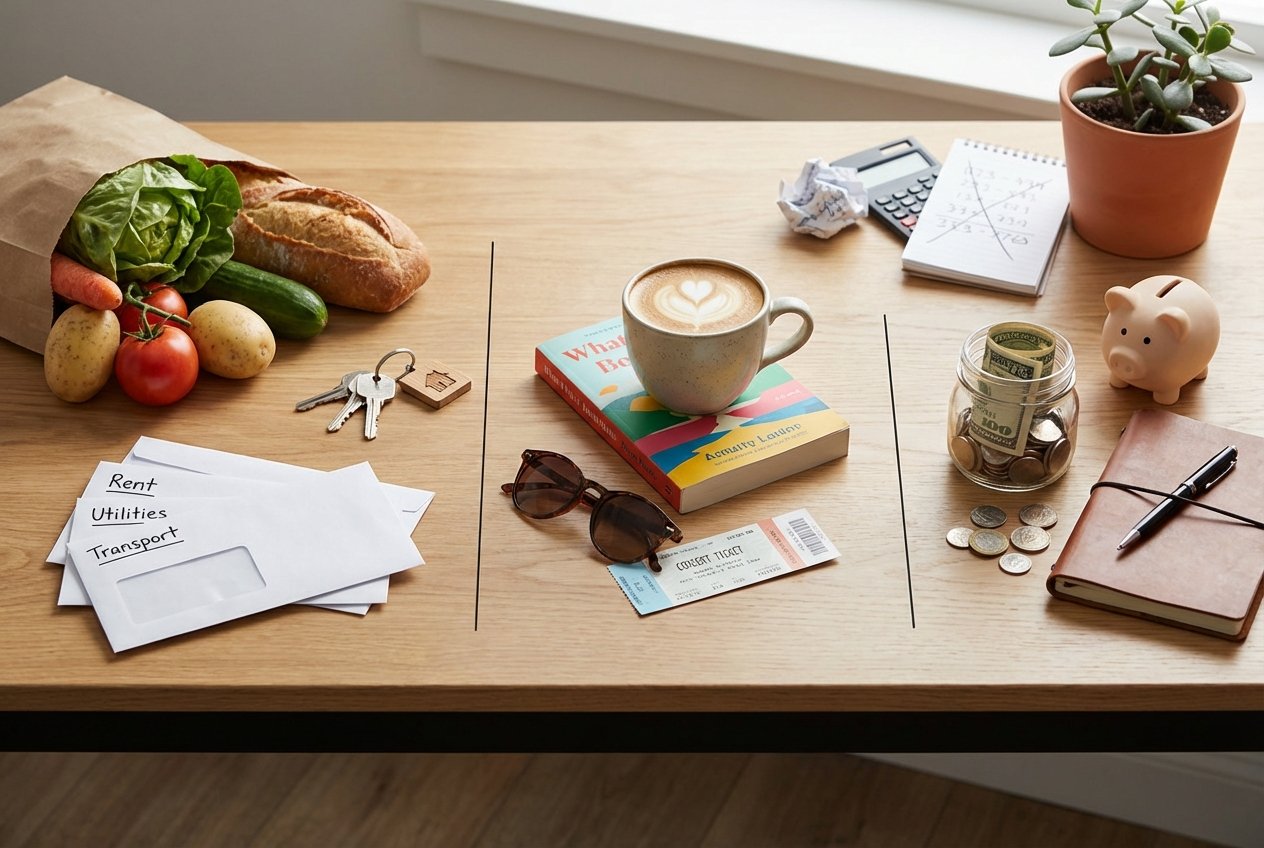
- Protect the Four Walls first: Housing, utilities, basic groceries, and essential transportation take absolute priority over credit card minimums, subscriptions, or discretionary meals out.
- Build a $1,000 cash shield: Before aggressively paying down debt or investing, park an initial emergency buffer in a dedicated high-yield savings account. Without this shield, any minor auto repair lands back on a credit card.
- Plan for non-monthly sinking funds: Car registrations, holiday gifts, and insurance premiums are predictable annual events. Divide them by 12 and reserve the cash monthly so they never surprise your checking account.
- The Producer mindset: Stop viewing budgeting as deprivation. A budget is simply a tool to direct your surplus into cash-flowing assets and debt elimination.
1. Why Most Budgets Fail Within 30 Days
Almost everyone has started a budget only to abandon it three weeks later.
You download an app, connect your bank logins, categorize past spending, and decide to slash your restaurant budget by 80%. By day twenty, an unexpected car tire blows out, your favorite takeout spots break your limits, and you feel like a failure.
The failure is not personal lack of discipline. The failure is following a static monthly plan that ignores how cash actually moves.
Bills do not wait for monthly averages. If your rent and auto insurance total $1,800 on the first of the month, but your biweekly paycheck only brings home $1,400 on the third, you are running an overdraft deficit even if your month-end spreadsheet balances on paper.
The Core Truth: A budget is not a post-mortem record of where your money vanished last month. It is an active blueprint that tells your money where to go before payday arrives.
2. The Non-Negotiable Rule: Protect the Four Walls
When money is tight, collectors and credit card companies call the loudest. They demand minimum payments, late fees, and immediate settlements.
In Stage 1 of the From Debt to Wealth roadmap, we silence the noise and focus on survival. You must protect your **Four Walls** before paying a single dollar toward unsecured debt or discretionary wants:
- Shelter: Rent or mortgage payments to keep a roof over your head.
- Basic Utilities: Electricity, water, and heating to keep your home functional.
- Food: Modest, nutritious groceries to sustain your household (not dining out).
- Transportation: Fuel and basic transit passes so you can travel to work and earn your paycheck.
Priority Warning: Never skip your rent or grocery money to make a credit card payment. An unsecured credit card cannot evict you from your home. Protect your foundation first.
3. The 5-Step Cash Flow Execution System
Follow this direct process to build a working system:
Step 1: Calculate Your Reliable Net Income
Use your exact take-home pay after taxes and mandatory employer deductions. If you are a salaried employee, look at your actual bank deposits. If your income is irregular or gig-based, baseline your budget against your lowest-earning month from the past six months. Any surplus in strong months becomes extra fuel for your emergency cushion.
Step 2: Map Your Bills to a Paycheck Calendar
Do not group all your expenses into a single monthly bucket. List every bill alongside its exact due date and pair it with the specific paycheck that funds it. This eliminates mid-month cash shortages and prevents bank overdraft fees.
Step 3: Build Your Initial $1,000 Cash Shield
Before launching an aggressive debt snowball, set aside a starter emergency buffer of $1,000 in an isolated high-yield savings account. That cash shield sits between your life and credit cards, ensuring a flat tire or dental copay does not throw you back into high-interest debt.
Step 4: Establish Realistic Discretionary Envelopes
Slashing personal spending to zero creates psychological rebellion. Set realistic, modest weekly cash allowances for dining, coffee, or entertainment. When that envelope is empty, spending pauses until the next scheduled paycheck.
Step 5: Run a 10-Minute Weekly Money Check-In
Pick one morning each week to spend ten minutes reconciling your numbers. Review transactions cleared, confirm upcoming auto-drafts for the following seven days, and adjust before a minor mistake turns into a major deficit.
4. Choosing Your Method: Paycheck vs. 50/30/20 vs. Zero-Based
Different financial stages require different tools. Here is how the primary budgeting methods compare:
| Budgeting System | How It Operates | Best For | Drawbacks to Watch |
|---|---|---|---|
| Paycheck Bill Calendar | Assigns specific expenses directly to the paycheck that precedes their due dates. | Living paycheck-to-paycheck, irregular income, or managing tight cash buffers. | Requires updating each pay cycle. |
| 50/30/20 Framework | Splits net income: 50% Needs, 30% Wants, 20% Savings and Debt Elimination. | Stable earners who want a broad benchmark without tracking every receipt. | Fails in high-cost-of-living areas where basic rent alone consumes 50% of income. |
| Zero-Based Allocation | Income minus all expenses, savings, and debt payoffs equals exactly zero every cycle. | Aggressive debt payoff (Stage 2) and maximizing every dollar of surplus. | Requires high discipline to record every transaction. |
5. Sinking Funds: Eliminating the “Surprise Expense”
A major reason households abandon their budgets is the so-called “surprise” bill.
Car insurance premiums, annual vehicle registrations, holiday shopping, back-to-school supplies, and routine dental visits are not emergencies. They happen every single year with absolute regularity.
The solution is a **sinking fund**.
Take the expected annual cost of each irregular bill, divide it by 12, and transfer that exact amount into dedicated savings buckets every month. When the $600 auto insurance bill arrives in six months, the cash is already sitting in your account waiting to be deployed.
The Peace of Mind Shift: When an annual bill arrives and you already have the money sitting in a sinking fund, an event that used to trigger panic becomes a routine, five-second transaction.
Step 1: Put Your Cash Flow on Autopilot
Stop using messy spreadsheets that break when life happens. Map your bills to your actual paydays, set up digital envelopes, and track your cash flow privately with the Beelinger Budget app.
Step 2: Build a Personalized Wealth Roadmap
Need an objective assessment of your spending ratios, debt payoff sequence, or savings targets? Work with Beelinger Money Coach to review your numbers, eliminate hidden cash leaks, and build an aggressive plan toward financial freedom.
Frequently Asked Questions
What should I do if my expenses exceed my income?
Focus entirely on your Four Walls: shelter, basic utilities, food, and necessary transportation. Pause all discretionary spending, call service providers to negotiate lower rates, and look for immediate ways to boost short-term income. Avoid taking high-interest cash advances or payday loans.
How much should a beginner save for an emergency fund?
Start with a target of $1,000 in an accessible high-yield savings account. Once your high-interest credit card debt is eliminated in Stage 2, expand that fund to cover three to six months of essential living expenses.
Is the 50/30/20 rule realistic for everyone?
No. If you live in an expensive metropolitan area, your basic housing and utilities may take up 60% or more of your take-home pay. Start with a baseline that reflects your reality, such as 70/20/10, and work toward lower overhead over time.
How often should I review my budget?
Run a quick 10-minute review every week to ensure transactions match your plan. Conduct a comprehensive review once a month before your first paycheck arrives, adjusting categories based on upcoming seasonal expenses.
Sources & Reference Material
- Consumer Financial Protection Bureau: Weighing Needs and Wants
- CFPB: An Essential Guide to Building an Emergency Fund
- Beelinger: Cash Flow Budget & Bill Calendar Tool
- Beelinger Money Coach: Behavioral Wealth Roadmap
- Beelinger Tools: Free Net Income & DTI Budget Calculator
Disclaimer: This content is for educational purposes only. Financial plans, tax situations, and debt strategies should be tailored to individual household circumstances. Consult qualified professionals for specific accounting or legal advice.
More from Beelinger
-
budgeting how to stop emotional spending
Where this fitsSurvival Understand Money Start the Survival track →Ask Money Coach about your next step →
-
budgeting Holiday Travel Budgeting: Save for Flights and Gifts at the Same Time
Stage 1 Playbook • Cash Flow Timing • Sinking Funds Holiday Travel Budgeting: Save for Flights and Gifts…
-
budgeting Ditch Spreadsheet Budgets: Build a Real Cash-Flow System
Track 1: Survival · Step 1 of 7Next step →View the full track Stage 1 Playbook • Cash…
-
budgeting How to Master the 50/30/20 Rule When You Hate Math
Track 1: Survival · Step 3 of 7← Previous stepNext step →View the full track Stage 1 Playbook…