The Budgeting Trap: Why Your Spreadsheet Is a Liar
Obsessing over $4 coffees while ignoring an $800 car note and 24% credit card APR is financial theater. Discover why micro-budgeting fails, how to audit your locked-in structural overhead, and how to build a cash flow system that actually works.
Editorial Notice: This article provides personal finance analysis and cash flow architecture education. It challenges traditional micro-budgeting approaches in favor of structural cost reduction, negative-interest elimination, and automated cash management.
The Reality Check (Read This First)
- The spreadsheet illusion: Traditional budgets fail because they assume a mathematically “normal” month that never exists in real life. Unplanned expenses inevitably break rigid category caps, triggering guilt and abandonment.
- Decision fatigue kills discipline: Wasting mental willpower tracking $3 convenience items leaves zero energy for high-leverage moves like restructuring an auto loan or changing health coverage.
- Structural overhead dictates your life: Housing, transportation, debt service, and taxes represent roughly 75% to 85% of your total outflows. You cannot save your way to wealth by trimming discretionary sand while your fixed rocks are oversized.
- Play architect, not clerk: Stop manually categorizing past transactions. Automate savings and debt payments the morning your paycheck clears, and let your fixed bills run through an isolated account.
- The 50% Rule: If your locked-in structural costs exceed 60% of your take-home pay, no coupon-clipping will fix your cash flow. You have a structural overhead problem.
1. The Spreadsheet Delusion: Precision Without Progress
Financial media has sold a pervasive myth: that if you spend enough hours color-coding Excel cells and logging every minor receipt, you will achieve financial freedom.
It feels productive. You download an app, connect your accounts, and look at pie charts displaying your past expenses down to the cent.
Here is why your spreadsheet is lying to you: precision is not progress.
Traditional budgeting is built on the fantasy of a “normal month.” In the real world, a normal month does not exist. In January, it is an emergency vet visit; in February, a cracked windshield; in March, an unexpected school fee or plumbing call.
When real life inevitably punctures your arbitrary spending categories, the “What-the-Hell” psychological effect kicks in. Because you went $60 over your dining category, you feel you have failed the entire budget, and you stop tracking entirely. A system that requires perfection in an unpredictable world is designed for collapse.
2. The Psychological Trap: Decision Fatigue and Scarcity
Traditional micro-budgeting turns you into an unpaid data entry clerk for your own household.
Spending mental bandwidth deciding whether a protein bar at a gas station is “Groceries” or “Personal Care” depletes your finite daily willpower. By the time you need to make high-leverage financial decisions—such as auditing your insurance policies or negotiating a bill—you are exhausted.
Worse, it breeds an obsessive scarcity mindset. Every minor transaction becomes an emotional negotiation filled with guilt. Wealth builders do not win by mastering the art of self-deprivation; they win by designing an operational system where their future is funded automatically before everyday spending begins.
The Core Principle: You cannot scrimp your way to sovereignty. Cutting a $5 coffee saves you $150 a month, but fixing an 84-month auto loan or refinancing a high-interest credit card balance frees up $500 to $800 every single month with zero daily effort.
3. The 4 Big Rocks Buried in Your Budget
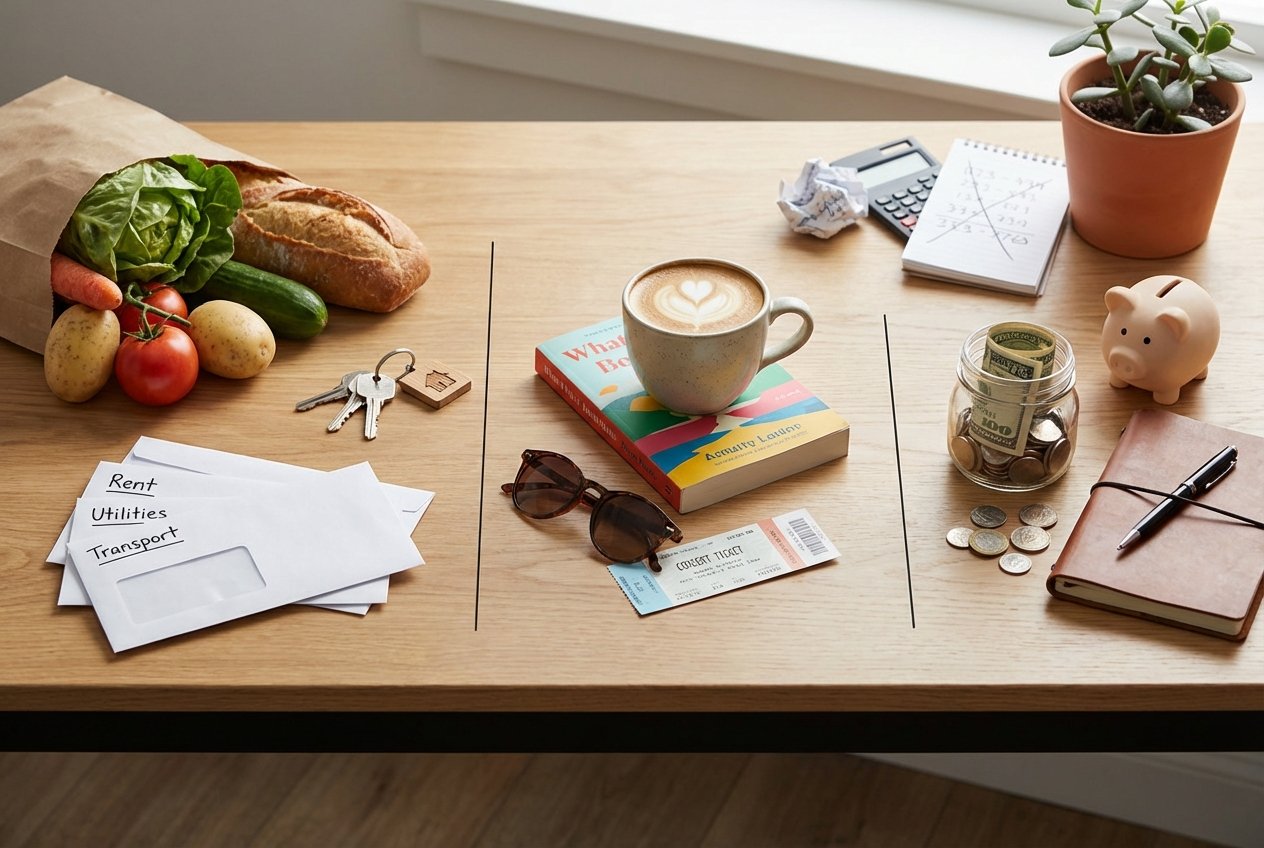
In the “Big Rocks” theory of cash flow, your monthly financial life is determined by four structural commitments that you made once and now pay for every thirty days:
| The Structural Rock | The Common Earner Trap | The Wealth Builder Action |
|---|---|---|
| 1. The Driveway Anchor (Vehicle) | Financing a $45,000 crossover over 72 to 84 months. Monthly note + insurance + fuel consumes $900 to $1,100/mo. | Cap total transportation (payment, insurance, fuel) below 15% of net pay. Sell the status symbol; drive reliable depreciated equity. |
| 2. The Housing Trap (Shelter) | Maxing out bank pre-approvals to buy more square footage than needed. Mortgage or rent exceeds 40% of income. | Cap shelter at 30% to 35% of net pay. Downsize or geo-arbitrage. Reducing rent by $400/mo is worth 1,000 skipped coffees. |
| 3. The Interest Bleed (Bad Debt) | Carrying $8,000 on credit cards at 24.99% APR while paying minimums and trying to save money. | Execute Stage 2 triage. Direct 100% of discretionary margin to wipe out 24% debt. Paying off credit card debt delivers a guaranteed 24% return. |
| 4. The Tax Leak (Lack of Shelter) | Failing to utilize pre-tax 401(k) matches, HSAs, or tax-advantaged accounts while spending hours clipping coupons. | Shield your income legally. A maxed HSA saves $800 to $1,200 in federal and FICA taxes automatically every single year. |
The Structural Overhead Audit
Calculate your Fixed-Cost Ratio. If your housing, vehicles, and debt minimums eat more than 60% of your take-home pay, your budget is structurally locked.
$2,680.00 / month
63.8%
Moderate Overhead Squeeze
*Healthy wealth-builder baseline is 50% or less. If your ratio exceeds 65%, your stress is driven by fixed structural contracts, not daily discretionary purchases.
5. The Anti-Budget Blueprint: Automating the Outcome
Stop playing bookkeeper. Instead of tracking where your money went after it left, build an **Anti-Budget** that dictates where it goes the moment it arrives:
- Split Your Payday Direct Deposit: The morning your paycheck arrives, automatically divert your savings and debt acceleration into separate silos. If your target is saving 15%, that cash leaves before you open your banking app.
- Isolate Your Fixed Bills: Keep a dedicated “Bills Only” checking account. Automatically transfer the exact dollar amount needed to cover your rent, car note, and utility calendar. Never swipe the debit card linked to this account.
- Spend the Remainder with Zero Guilt: Whatever remains in your everyday checking account is yours to spend freely. You do not need to track lattes, lunches, or haircuts. Because your future is already funded and your fixed bills are safely isolated, you cannot accidentally overspend.
The Final Takeaway: Stop treating personal finance like an ongoing punishment. Fix the four Big Rocks, automate your baseline transfers, and spend your mental energy building assets that buy back your time.
Put Your Cash Flow on Autopilot
Ditch the spreadsheets that make you feel guilty. Map your essential due dates, track your emergency buffer, and automate your paycheck with the free, private Beelinger Budget system.
Frequently Asked Questions
Does the anti-budget mean I can spend whatever I want?
Yes, within the boundaries of what remains after your future is paid. Once your automated savings, retirement contributions, emergency reserve transfers, and fixed bill obligations are deducted on payday, the remaining balance can be spent guilt-free without micro-tracking.
What if my fixed overhead already exceeds 65% of my pay?
You cannot solve a 65% fixed overhead problem by cutting out small pleasures. You must attack the Big Rocks: consider refinancing or selling a vehicle with a high monthly payment, finding roommates or downsizing shelter, or consolidating high-interest credit card debt using a 0% balance transfer.
Why does the article argue that coffee and small expenses are a distraction?
Because small discretionary cuts produce negligible financial returns while causing high mental fatigue. Cutting a $4 coffee five days a week saves $80 a month, but eliminating a single $500 monthly car note or getting rid of 24% credit card interest delivers immediate, life-changing financial margin.
How do I identify my own Big Rocks?
Pull your last 90 days of bank and credit card statements. Cross out every transaction under $100. The remaining large, recurring charges represent the four to five structural choices that dictate your financial life.
Sources & Reference Material
- Federal Reserve: Consumer Credit (G.19) Report on Revolving Household Debt
- Consumer Financial Protection Bureau: Auto Loan Term Lengths & Cost Analysis
- Beelinger: Private Cash Flow & Budget Calendar Tool
- Beelinger: Free Debt Snowball & Payoff Calculator
Financial architecture guidelines reflect audited consumer benchmarks. Fixed-cost ratios and debt payoff timelines should be calibrated to your local cost of living and household income.
More from Beelinger
-
budgeting how to stop emotional spending
Where this fitsSurvival Understand Money Start the Survival track →Ask Money Coach about your next step →
-
budgeting Holiday Travel Budgeting: Save for Flights and Gifts at the Same Time
Stage 1 Playbook • Cash Flow Timing • Sinking Funds Holiday Travel Budgeting: Save for Flights and Gifts…
-
budgeting How to Master the 50/30/20 Rule When You Hate Math
Track 1: Survival · Step 3 of 7← Previous stepNext step →View the full track Stage 1 Playbook…
-
budgeting Why Most Americans Live Paycheck to Paycheck
Beelinger Editorial | Household Finance The Illusion of Prosperity: Why So Many Americans Live One Paycheck From Trouble…