Traditional 401(k) vs. Roth 401(k) vs. Roth IRA: The Clear Decision Matrix
You eliminated toxic debt and built an emergency buffer. Now comes the ownership phase. Discover the exact criteria for routing your surplus capital across pre-tax and post-tax buckets without overpaying the IRS.
Educational Notice: This guide provides tax location and asset structuring education, not individualized legal or tax advice. IRS contribution limits, income phaseouts, and state tax treatments are subject to change. Consult a qualified CPA regarding your specific tax bracket.
The Rules of Account Selection (Read This First)
- Order of operations: Always capture your full employer 401(k) match first. Unmatched dollars should then be routed to an account based on your tax bracket and flexibility needs.
- The 22% bracket threshold: If your marginal federal income tax bracket is 12% or 22%, post-tax Roth accounts usually offer the highest long-term value. In the 32% or higher brackets, pre-tax deductions provide stronger upfront shelter.
- Roth IRA control advantage: A Roth IRA offers better investment choices, lower internal fund fees, and the ability to withdraw original contributions at any time without taxes or penalties.
- 2026 Contribution Caps: Workplace 401(k) deferrals max out at $24,500, while individual IRAs are capped at $7,500 (plus catch-up allowances for age 50+).
- Tax diversification: True wealth builders do not put 100% of their money into a single tax treatment. They enter retirement with both pre-tax and tax-free assets to control their annual tax bill.
1. Entering Stage 3: Moving from Defense to Ownership
In Stage 1, you plugged silent cash leaks and secured an emergency cash cushion. In Stage 2, you eliminated toxic credit card balances and high-interest loans.
Now you enter Stage 3: Asset Ownership.
Your monthly margin is no longer consumed by minimum debt payments or panic spending. Your cash is ready to work. But picking broad-market index funds is only half the battle. You must choose the right legal container for those funds.
Choosing between a Traditional 401(k), a Roth 401(k), and a Roth IRA is not about predicting future stock prices. It is a calculated decision based on tax location, liquidity access, and income thresholds.
The Core Principle: It is not just what your assets earn; it is what you keep after federal and state taxes. Placing the right investments into the right tax containers protects decades of compound growth from future tax hikes.
2. The Three Buckets: A Direct Feature Breakdown
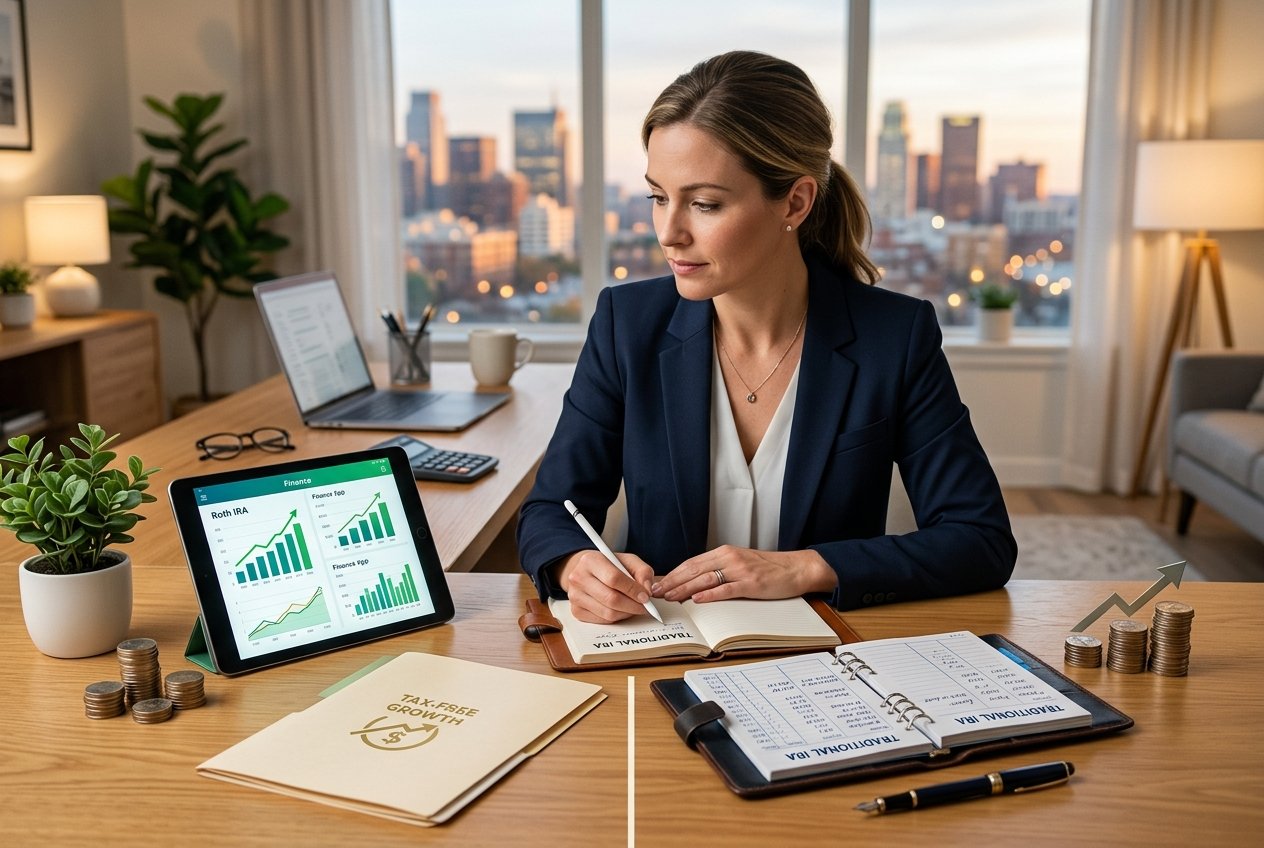
To make an informed decision, compare the three accounts across their core mechanical features:
| Feature | Traditional 401(k) | Roth 401(k) | Roth IRA |
|---|---|---|---|
| Tax Treatment on Contribution | Pre-tax (reduces current taxable income) | Post-tax (no upfront deduction) | Post-tax (no upfront deduction) |
| Qualified Withdrawal Tax | 100% taxed as ordinary income | 100% Tax-Free | 100% Tax-Free |
| 2026 Contribution Limit | $24,500 (combined with Roth 401k) | $24,500 (combined with Trad 401k) | $7,500 ($8,600 if age 50+) |
| Income Eligibility Cap | None (available to all participants) | None (available to all participants) | Phaseouts apply based on MAGI |
| Early Contribution Access | Penalties & taxes apply | Pro-rata tax rules apply | Contributions withdrawn anytime penalty-free |
| Investment Choice Range | Limited to employer’s plan menu | Limited to employer’s plan menu | Virtually unlimited (any stock, ETF, index fund) |
3. The Selection Criteria: Which Bucket Wins for You?
Use these specific financial checkpoints to determine where your next dollar should go:
Look at your federal tax bracket on your latest return:
- If you are in the 10%, 12%, or 22% bracket: Choose the Roth options (Roth 401k or Roth IRA). Paying income taxes today while rates are relatively low allows 100% of your multi-decade compound growth to be withdrawn tax-free in retirement.
- If you are in the 32%, 35%, or 37% bracket: Choose the Traditional 401(k). The immediate upfront tax deduction saves you significant cash today, which can be reinvested into other productive assets.
- If you are in the 24% bracket: You sit in the pivot zone. Many wealth builders split contributions 50/50 between pre-tax and Roth to hedge future political and tax uncertainty.
Not all workplace retirement plans are created equal. Review your 401(k) fund menu:
- If your employer plan offers high-cost, actively managed mutual funds with expense ratios above 0.50% or charges administrative maintenance fees, limit your 401(k) contributions to the company match. Route your remaining capital to an independent Roth IRA where you can buy zero-fee index funds (expense ratios under 0.04%).
- If your employer plan provides institutional-grade Vanguard or Fidelity index funds with rock-bottom expense ratios, using the workplace Roth 401(k) offers great convenience and higher annual contribution limits.
While retirement assets should generally remain untouched until retirement, financial life can be unpredictable:
- A Roth IRA provides structural flexibility. Because you funded it with after-tax money, IRS rules allow you to withdraw your direct contributions at any time for any reason with zero taxes and zero penalties (only investment earnings are subject to withdrawal restrictions before age 59½).
- 401(k) plans lack this flexibility. Hardship distributions or plan loans come with administrative hurdles, potential penalties, and immediate repayment triggers if you change jobs.
4. The Optimal Wealth Builder Contribution Sequence
When you have surplus cash to allocate in Stage 3, do not guess. Follow this mathematical order of operations:
-
Step 1: Capture the Full 401(k) Match.
Route enough money into your workplace plan (Traditional or Roth) to capture 100% of the employer matching dollars. This is an instant 50% to 100% return on capital. -
Step 2: Max Out Your Roth IRA ($7,500).
Open an account at an independent brokerage like Fidelity, Vanguard, or Schwab. Direct surplus cash here to capture unlimited low-fee investment choices and completely tax-free qualified withdrawals. -
Step 3: Return to Your Workplace 401(k).
If you max out the Roth IRA and still have surplus monthly cash flow, return to your workplace 401(k) and scale contributions toward the $24,500 annual limit. Select Traditional if you need current tax relief, or Roth 401(k) if you prefer lifetime tax-free income. -
Step 4: Taxable Brokerage Account.
Once tax-advantaged accounts are fully funded, route excess cash flow into a standard taxable brokerage account invested in tax-efficient broad-market index ETFs (like VOO or VTI).
5. The RMD Reality: Age 75 Rules
Under current legislation (SECURE 2.0), traditional pre-tax accounts face mandatory Required Minimum Distributions (RMDs) starting at age 73 (moving to age 75 for individuals born in 1960 or later).
If you have millions saved in a Traditional 401(k), the IRS forces you to withdraw large sums every year, which get added directly to your taxable income. This can push you into higher tax brackets and trigger higher Medicare Part B and Part D premiums.
Both Roth IRAs and Roth 401(k)s are exempt from lifetime RMDs. Your assets can sit inside the account and compound tax-free for your entire lifetime, giving you complete control over your retirement withdrawals.
Model Your Paycheck Impact Before You Elect
See how adjusting your Traditional vs. Roth contributions changes your take-home pay. Run your numbers through the free Beelinger 401(k) Calculator.
Frequently Asked Questions
Can I contribute to both a 401(k) and a Roth IRA in the same year?
Yes. The contribution limits are separate. In 2026, you can contribute up to $24,500 to a workplace 401(k) and up to $7,500 to an individual IRA, assuming you meet income eligibility requirements.
What happens if my company doesn’t offer a Roth 401(k)?
Contribute to the Traditional 401(k) up to the company match. After securing the match, open an independent Roth IRA at a brokerage to access the benefits of tax-free growth.
Are employer matching contributions placed in my Roth account?
Historically, all employer matching funds had to be placed in pre-tax traditional accounts. Under SECURE 2.0 rules, employers can offer matching funds directly into Roth accounts, but those matching dollars are reported as taxable compensation in the year received.
When can I withdraw money from a Roth IRA tax-free?
You can withdraw your original contributions at any time without taxes or penalties. To withdraw investment earnings tax-free, you must be at least age 59½ and the account must have been open for at least five tax years.
Sources & Reference Material
- IRS: 401(k) Plan Rules and Elective Deferral Limits
- IRS: Roth IRA Contribution and Distribution Requirements
- U.S. SEC: Retirement Plans and Account Structure Guide
- Beelinger: 401(k) Paycheck Modeling Tool
Contribution caps, tax brackets, and federal retirement legislation reflect 2026 statutory rules. Tax consequences vary based on individual household filing status and state laws.
More from Beelinger
-
money-brief The 401(k) Tax Trap: Why Pre-Tax Savings Might Be Costing You More Than You Think
Stage 3 • Asset Ownership & Tax Strategy The 401(k) Tax Trap: Why Pre-Tax Savings Might Be Costing…
-
money-brief How Much Should You Put in Your 401(k)
The Wealth Mindset Blueprint • Stage 3 Compounding How Much Should You Put in Your 401(k)? Start With…
-
money-brief Roth vs Traditional IRA: Which Saves You More Money?
Roth IRA vs. Traditional IRA: Which Is Best for You in 2026? Choosing between a Roth IRA and…